Skip to content
delhi, Delhi, 110034

Business hours

SIP & Mutual Funds Investment Services – Finguide Buddy

Monday
24 hours
Tuesday
24 hours
Wednesday
24 hours
Thursday
24 hours
Friday
24 hours
Saturday
24 hours
Sunday
24 hours

You can anytime during the day with your query.

9891645052

Latest Posts & Updates

Fresh stories, announcements and offers about Investment Company, Finance broker, Investment service, straight from our business.

Investor Personality Types (BB&K Model)

Do you know which type of investor you are? 🤔 As per Bailard, Biehl & Kaiser (BB&K) Model, investors are divided into 5 categories: 1️⃣ Adventurer 🚀 – High risk taker, seeks big returns, confident & independent. 2️⃣ Celebrity 🌟 – Loves market trends & attention, follows buzz & hot tips. 3️⃣ Individualist 🧑‍💼 – Practical, disciplined, research-based, takes calculated risks. 4️⃣ Guardian 🛡️ – Safety first, conservative, prefers FDs, bonds & secure assets. 5️⃣ Straight-Arrow 🎯 – Balanced, neither too risky nor too cautious, seeks growth with safety. 📌 In short: Every investor has a unique style → Understanding this can help in making informed investment decisions. 💡

Read full post

💵 What are Foreign Currency Convertible Bonds (FCCBs)?

👉 **FCCBs** are special types of bonds issued by Indian companies to raise money in **foreign currency** (usually US dollars) from international markets. ✅ Key Features: * 📑 **Debt Instrument**: They are foreign currency denominated **debt certificates** issued by firms. * 💰 **Payments in Foreign Currency**: Both interest and principal repayment are done in foreign currency. * 🔄 **Convertible Option**: Investors have the option to convert these bonds into the company’s **equity shares** before maturity. ⚡ **Why do companies issue FCCBs?** * To raise funds at lower interest costs. * To attract global investors. * To provide flexibility with the conversion feature. 📌 In short: FCCBs = **Debt + Equity Option**, making them attractive to both companies and international investors. 🌐📈

Read full post

🏠 Resident or 🌏 NRI? Know Your Tax Status!

Do you know your residential status as per the Income Tax Act? It’s important because your tax liability in India depends on whether you are a Resident or a Non-Resident (NRI). 👉 You are a Resident in India if: ✅ Stayed in India for 182 days or more during the financial year, OR ✅ Stayed in India for 60 days or more in that year + 365 days or more in the last 4 years. 👉 You are an NRI if: ❌ Stayed in India for less than 182 days in the financial year. 📌 In short: 182 days or more = Resident 🏠 Less than 182 days = NRI 🌍 💡 Know your status, plan your taxes better!

Read full post

Market risk, also known as systematic risk, is unavoidable in equity investments because it arise…

Market risk, also known as systematic risk, is unavoidable in equity investments because it arises from factors that impact the entire market or economy. These factors include: Economic Factors: Changes in GDP, inflation, interest rates, or unemployment. Political Factors: Government policies, elections, or geopolitical events. Social Factors: Demographic changes, consumer behavior, or cultural shifts. Since these factors influence all listed stocks to some extent, market risk cannot be eliminated through diversification or other investment strategies. It is inherent to investing in equities.

Read full post

Important Update for NRI Investors: Mandatory TIN Requirement under FATCA/CRS

As per FATCA/CRS compliance rules, the country of tax residency declared by investors must be reported to the regulatory authorities, including the Central Board of Direct Taxes (CBDT). It has been observed that in several cases, Tax Identification Numbers (TINs) provided by NRI investors are either missing or invalid. CBDT has already started issuing notices for defective records, and each such defective record can attract a penalty of ₹5,000. 🔴 Effective from August 25, 2025: 1️⃣ New NRI Applications – All new applications must include a valid TIN. 👉 Applications without TIN will be rejected. 2️⃣ Existing NRI Investors – If a valid TIN is not provided, future transactions will be restricted. 👉 A remediation process for updating existing records has already been initiated. ✅ Action Required from Investors All NRI investors are requested to provide a valid TIN at the time of investment. Existing NRI clients must update their records with AMCs/RTAs to avoid any restrictions or penalties. Kindly treat this as urgent and important to ensure seamless processing of your mutual fund investments. For any assistance or clarification, feel free to reach out to me. 📌 This update is being shared in the interest of compliance and smooth investment experience for all NRI investors. — Rajesh Kathpalia, CFP Finguide Budddy, AMFI-Registered Mutual Fund Distributor ( ARN -257079)

Important Update for NRI Investors: Mandatory TIN Requirement under FATCA/CRS post imageRead full post

📊 Understanding Portfolio Overlap in Mutual Funds

When investing in mutual funds, many investors choose multiple schemes from the same category (like Multi-Cap Funds) thinking it will diversify their portfolio. But the truth is, sometimes these funds hold many of the same stocks – this is called Portfolio Overlap. 👉 Example from the table: Axis Multi Cap Fund & Edelweiss Multi Cap Fund have 49% overlap – almost half of their holdings are the same. Kotak Multi Cap Fund & HDFC Multi Cap Fund overlap is just 16% – giving more diversification. ✅ Why is this important? If you invest in funds with a high overlap, you are not really diversifying – you’re just repeating the same stocks through different funds. True diversification comes from choosing funds with low to moderate overlap so that your portfolio covers different opportunities and reduces risk. 💡 Key Takeaway: Overlap below 20% = Good diversification Overlap 20-40% = Acceptable Overlap 40%+ = High duplication (be cautious) ✔️ Select the right funds with proper diversification ✔️ Avoid unnecessary duplication ✔️ Build a portfolio aligned with your financial goals 📞 Let’s review your portfolio together: ⚠️ Disclaimer: Mutual Fund investments are subject to market risks. Please read all scheme-related documents care

📊 Understanding Portfolio Overlap in Mutual Funds post imageRead full post

💡 The 8-4-3 Rule of Compounding – SIP Ka Magic! 💰

When you do a ₹30,000 monthly SIP: 🔹 It takes 8 years to reach your first ₹50 lakhs But here comes the surprise... 🔹 Just 4 years for the next ₹50 lakhs 🔹 And only 3 years for the third ₹50 lakhs! ✅ Compounding works slowly at first, then suddenly! 📲 Start your SIP with Finguide Buddy Zero service charge | Paperless process | App access | Tax-saving plans 📍 Serving: Pitampura | Bhiwani | Hisar | Haridwar | Delhi & NCR

💡 The 8-4-3 Rule of Compounding – SIP Ka Magic! 💰 post imageRead full post

🎓 Start SIP for Your Child’s Future

Looking to invest for your child's education, marriage or future goals? A Systematic Investment Plan (SIP) in mutual funds under your child's name is a smart, long-term move. Let’s simplify it for you! ✅ Minor’s PAN Not Mandatory As per rules, to open a minor folio, only the guardian’s PAN is mandatory. The child’s PAN is optional. 📑 Documents Required: Guardian’s PAN Proof of relationship (birth certificate, passport, or court order) 🏦 SIP Payment Flexibility You can start SIP from either the guardian’s bank account or the minor’s bank account. 🔁 However, all redemption will be credited only to the minor’s bank account—ensuring transparency and safety. ⏱️ Quick Process Folio creation takes just 2 working days, and SIP can begin right away! 🎯 Why Invest in Child’s Name? Helps build long-term financial discipline Keeps you goal-oriented (education, career, etc.) Teaches children good money habits 🔒 As per SEBI guidelines, children’s mutual funds have a 5-year lock-in or till the child turns 18—whichever is earlier. 💰 Tax-saving, goal planning, wealth creation—all start with just ₹500/month. ✅ No service charge | Easy mobile access | Online Onboarding | 📲 Call Finguide Buddy today – your AMFI Registered Mutual Fund Distributor in Delhi NCR, Hisar, Bhiwani & Haridwar.

🎓 Start SIP for Your Child’s Future  post imageRead full post

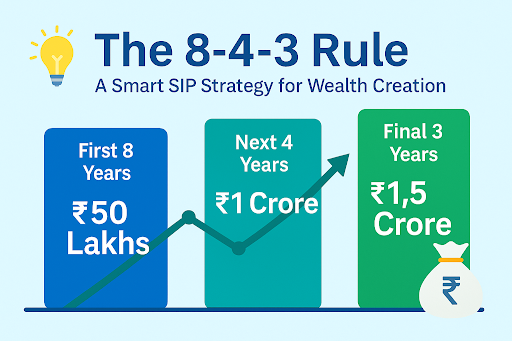
💡 8-4-3 Investment Rule in Mutual Funds : A Smart SIP Strategy for Wealth Creation 💰

Looking to grow your wealth through mutual fund investments? The 8-4-3 Rule can be your financial game-changer. It's a powerful, goal-oriented strategy that shows how consistent SIPs and compounding can help you build ₹1.5 Crore over 15 years! ✅ Here's how it works (based on ₹30,000/month SIP at 12% annual return): 🔹 First 8 Years ➡️ Your investment grows to ₹50 Lakhs 🔹 Next 4 Years ➡️ It doubles to ₹1 Crore 🔹 Final 3 Years ➡️ It grows to ₹1.5 Crore 📈 This strategy highlights the power of compounding, long-term SIP investment, and systematic wealth creation through mutual funds. Whether you’re planning for retirement, your child’s education, or buying your dream home, the 8-4-3 Rule helps you stay on track. 🌟 Stay invested. Stay disciplined. Let time and patience do the magic. 📲 Want to know how much wealth your SIP can create? 💰 Call us now and get a personalized calculation! 📞 Finguide Buddy 📍 AMFI-Registered Mutual Fund Distributor #SIP #MutualFunds #WealthCreation #FinancialPlanning #InvestmentTips #8_4_3Rule #PowerOfCompounding #BestSIPPlan #MutualFundSahiHai #GoalBasedPlanning #TaxSaving #LongTermInvestment #AMFIRegistered #FinguideBuddy #SIPCalculator

💡 8-4-3 Investment Rule in Mutual Funds : A Smart SIP Strategy for Wealth Creation 💰 post imageRead full post